
Reviewed by John Hu, founder of John Hu Migration Consulting and Registered Migration Agent (MARN 0746141).
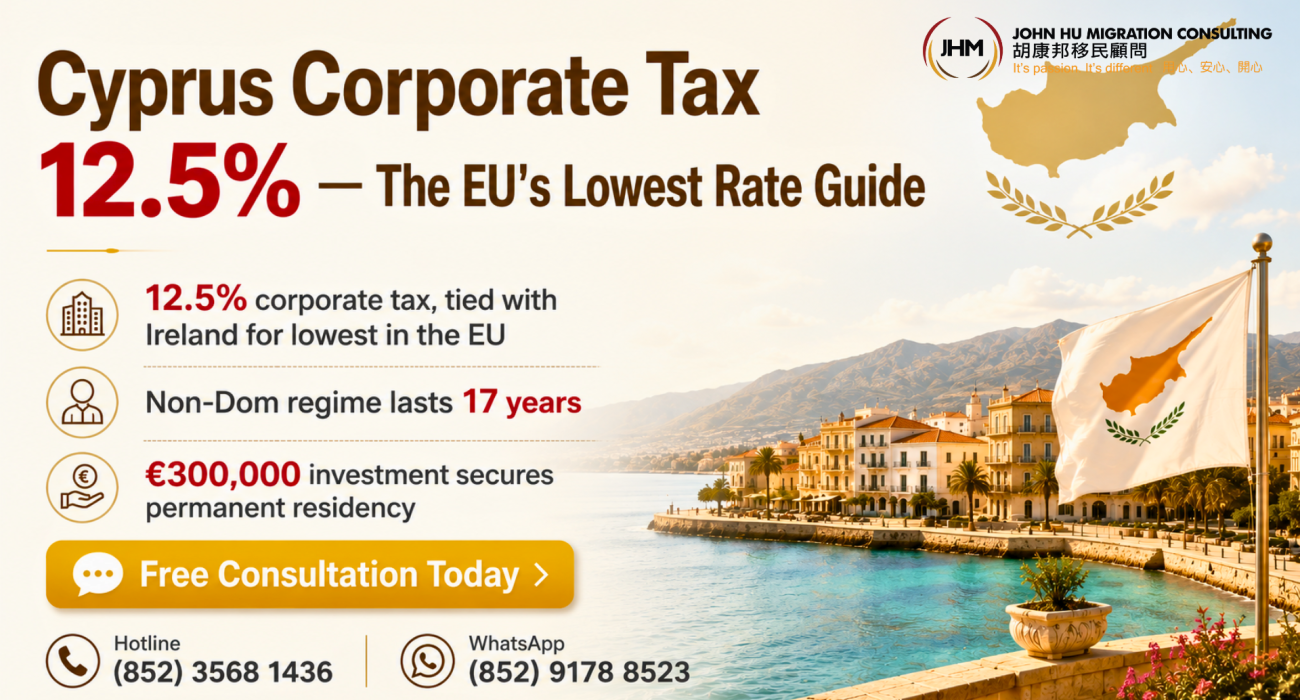
Cyprus’s corporate tax rate, held at 12.5%, is one of the core reasons the country is a go-to tax jurisdiction for global business and investors. As an EU member state, Cyprus offers a tax system designed to attract foreign investment.
This guide covers corporate tax, personal income tax, dividend tax and key exemptions, and explains why Cyprus’s investment residency program can be a legal route for Hong Kong investors to access the wider tax framework.
12.5% — One of the EU’s Lowest Rates
Cyprus applies a 12.5% corporate tax rate to taxable profit of companies registered in Cyprus, regardless of size or industry.
| Country | Corporate tax |
|---|---|
| Cyprus | 12.5% |
| Ireland | 12.5% |
| Hungary | 9% |
| Bulgaria | 10% |
| Greece | 22% |
| France | 25% |
| Germany | ~30% |
| Italy | 24% |
| Portugal | 21% |
Cyprus’s rate reflects a deliberate strategy, sustained since EU accession in 2004, to attract investment and develop a Europe–Middle East–Africa business hub.
Cyprus’s Full Tax System — What Investors Should Know
1. Corporate Income Tax
- 12.5% on taxable profit.
- Foreign subsidiary profits are typically exempt when participation-exemption conditions are met.
- Losses may be carried forward indefinitely.
2. Dividend Tax
- Foreign subsidiary dividends are exempt in most cases.
- Dividends paid to non-resident shareholders generally have 0% withholding tax.
- Dividends received from Cyprus companies are exempt.
3. Capital Gains Tax
- Share-sale gains, including foreign-company shares, are generally exempt.
- Cyprus real-estate gains are taxed at 20%; foreign real-estate gains are generally exempt.
4. Personal Income Tax
- Up to €19,500: 0%; €19,501–28,000: 20%; €28,001–36,300: 25%; €36,301–60,000: 30%; above €60,000: 35%.
5. Non-Domicile (Non-Dom) Regime
Eligible new residents may be exempt from Special Defence Contribution on dividends, bank interest and rental income. Non-Dom status can last 17 years from becoming a Cyprus resident.
6. Inheritance Tax
Cyprus has no inheritance tax.
7. Annual Wealth Tax
Cyprus does not levy an annual wealth or property tax.
8. VAT
- Standard rate: 19%.
- Reduced rates: 9% for hospitality/dining and 5% for selected essentials.
- New-build property is generally 19%, with a possible 5% rate for qualifying first-time buyers.
9. Double Tax Treaties
Cyprus has treaties with 65+ countries, helping cross-border investors reduce double taxation subject to the applicable rules.
Who Qualifies for Cyprus’s Tax Benefits?
- Tax residence: more than 183 days, or the 60-day rule where all additional business and residence conditions are met.
- Investment residency: a minimum €300,000 investment may secure legal residency under the applicable program, subject to current requirements.
Cyprus vs. Other EU Migration Programs
| Metric | Cyprus | Greece | Malta | Portugal |
|---|---|---|---|---|
| Corporate tax | 12.5% | 22% | 35% | 21% |
| Inheritance tax | None | Yes | Yes | Yes |
| Annual wealth tax | None | Yes | None | Yes |
| Non-Dom period | 17 years | 15 years | Available | 10 years |
| Double-tax treaties | 65+ | 57 | 70+ | 79 |
A Common Tax Structure Used by Hong Kong Investors
Some investors use Cyprus as a holding jurisdiction for regional investments, potentially combining the corporate rate, dividend treatment, capital-gains rules, EU legal framework and access to European credit.
Important: cross-border structures must be designed by qualified advisers familiar with Hong Kong, Cyprus, CFC and OECD BEPS rules.
Cyprus Permanent Residency — The Legal Gateway
- Minimum investment of €300,000 in real estate or an approved category.
- Minimum foreign income requirement may apply.
- Permanent-residency card and limited visit requirements, subject to the current rules.
- May cover a spouse and children under 25 in the same application.
- Tax residence and Non-Dom benefits still depend on meeting their own conditions.
FAQ
- If I just own property in Cyprus, do I automatically get the tax benefits?
No. Simply owning property doesn't grant tax benefits on its own — you need to establish tax residency (the 183-day or 60-day rule) or obtain permanent residency through investment to access the full tax advantage system.
- What happens after the 17-year Non-Dom period ends?
After 17 years, an investor is generally considered domiciled in Cyprus, at which point taxes like SDC, previously exempt, begin to apply. It's worth planning long-term tax and wealth transfer arrangements well before the 17-year window closes.
To fully understand how to obtain Cyprus permanent residency through investment and access its complete tax advantage system, see an overview of Europe’s immigration programs; to compare against other EU golden visa options, see Portugal’s Golden Visa 2026: Requirements, Fund Investment, and the Full Application Guide as a point of comparison.
Cyprus’s tax system offers genuine advantages — but to use it fully and in compliance with the rules, you need a complete roadmap designed by a team well-versed in both local residency status and international tax structuring:
- In-depth consultation on Cyprus’s permanent residency program — requirements, process, and a concrete timeline
- Connections to verified local tax lawyers and legal specialists in Cyprus
- Support designing an ownership structure and tax optimization plan suited to your specific circumstances
- Full cost transparency from day one — a detailed quote provided before any commitment is signed
Outcomes, processing times, and follow-on status arrangements vary by applicant background, case specifics, documentation completeness, and official approval requirements. The above is for reference only and does not constitute a guarantee of approval or investment advice.
📞 Enquiry Hotline: (852) 3568 1436 WhatsApp: (852) 9178 8523
Fill out our free assessment form to have our team assess a Cyprus tax advantage plan for your situation.